Complete Guide to EU VAT Invoice Requirements
Learn everything you need to know about EU VAT requirements – what is VAT invoice, when to issue it, and how to register for EU VAT. Find out how to create a VAT invoice in under 30 seconds.
VAT stands for value added tax and applies in more than 160 countries worldwide. Anyone running a small business that trades within the EU will sooner or later need to understand how VAT invoicing works, since the general framework is set at EU level while rates and some administrative details are defined nationally.
What VAT obligations do businesses from outside the EU have, and how do you register for VAT in an EU member state? This article walks through the questions that non-EU and EU companies most often ask when they start issuing VAT invoices, and shows how good invoicing software can make the whole process easier.
What Is a VAT Invoice?
A VAT invoice is an accounting document that lists the goods and services sold and confirms that VAT has been charged on them. In EU countries, a VAT invoice generally has to be issued no later than 15 days after the end of the month in which the goods or services were delivered, so it pays to create an invoice as soon as the sale is confirmed rather than leaving it until the deadline.
Because VAT invoices carry legal weight for both the seller and the buyer, they need to be accurate, sequentially numbered, and easy to retrieve later. This is exactly why many small business invoicing teams move away from spreadsheets and word processors toward dedicated invoicing software - it keeps every invoice template consistent and stores documents in one searchable place.
How to Register for VAT in the EU
You can register as a VAT payer in any EU country where you do business. If you trade with more than one EU country, it is worth registering for MOSS (the VAT Mini One Stop Shop), which lets you submit VAT through a single return instead of filing separately in every country where you have customers.
When Do You Have to Issue a VAT Invoice?
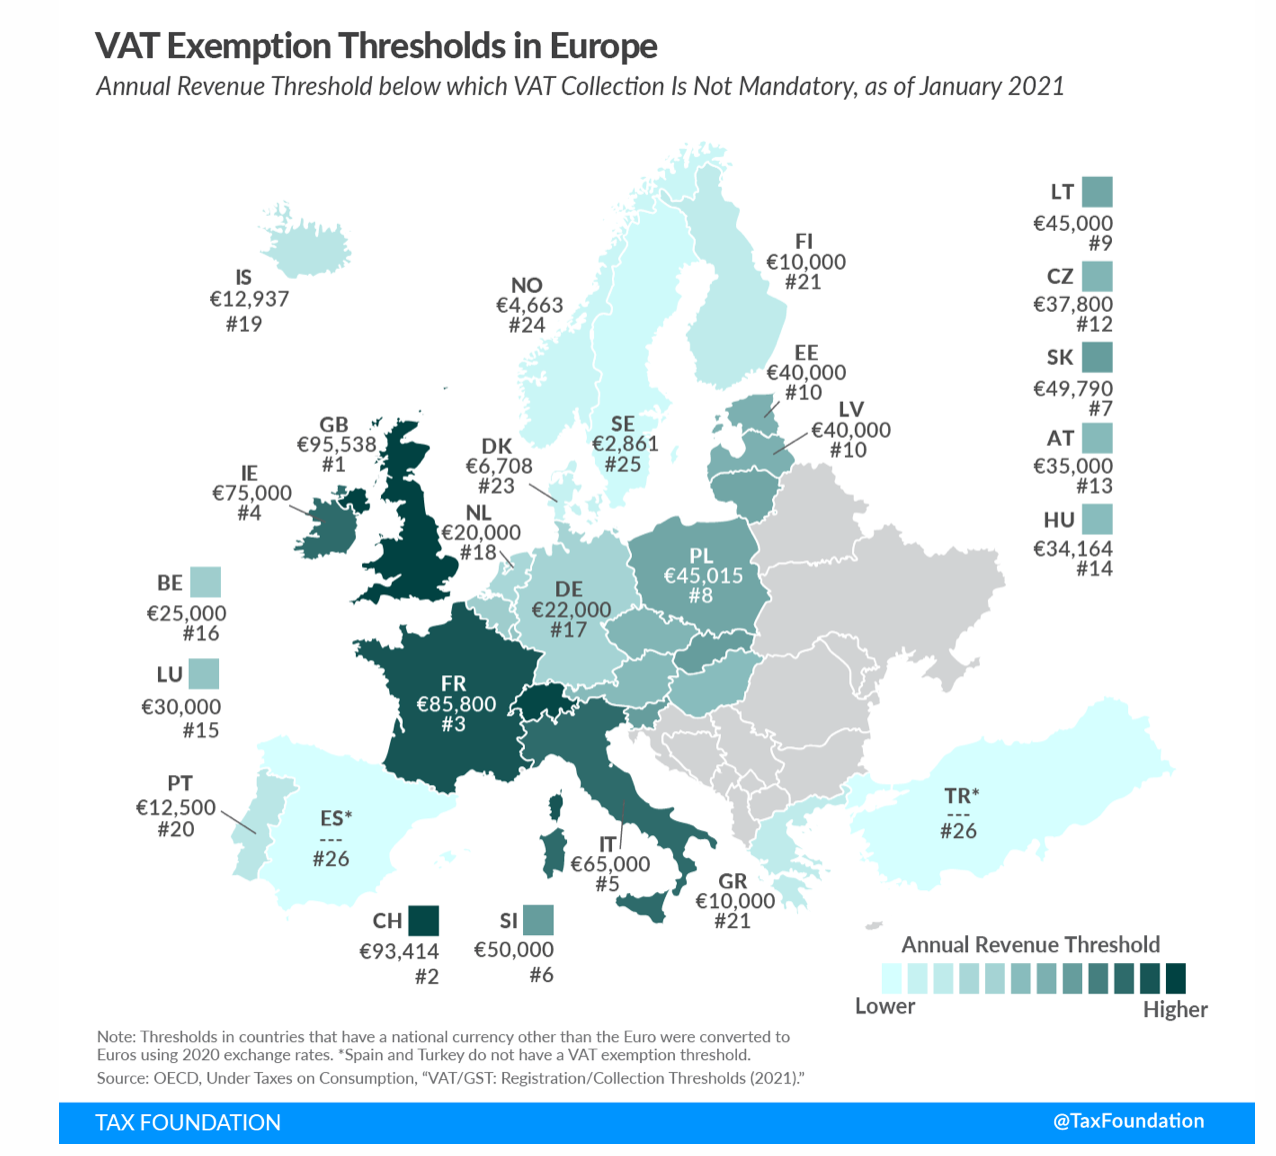
The obligation to issue a VAT invoice appears once you are registered as a VAT payer. So when does the obligation to register actually arise? There is no single answer, because every country applying VAT can set its own turnover thresholds. For example, in the UK the obligation to register for VAT appears once taxable turnover over the past 12 months exceeds £85,000.
To be sure about your own situation, check the regulations of the country where your company is registered. The infographic below gives a general overview of exemption thresholds across the EU.
Distance selling has its own set of rules. Since July 2021, a business that exceeds 10,000 EUR in cross-border sales of goods to consumers has to register for VAT in every country where those goods or services are supplied after the threshold is crossed. Only the first 10,000 EUR are taxed in the seller's home country.
What Must a VAT Invoice Include?
Creating a VAT invoice by hand means keeping track of a fairly long list of mandatory fields. A good invoice template built into your invoicing software will already contain all of them, which is one of the main reasons online invoicing tools are so popular with small businesses. Here is what a VAT invoice needs to include:
- Business name and address
- VAT number
- The invoice date and number
- The client's name and address, and VAT number if applicable
- Information about reverse charge if applicable (when your client is VAT registered)
- The VAT rate applied
- Total amount charged for each item
- Total amount due after VAT is added
- The currency that applies
Once you know which fields are required, the fastest way to stay compliant on every sale is to set them up once in an invoice template and reuse it for every VAT invoice, payment reminder, and recurring invoice you send afterwards.
EU businesses registered for VAT are obliged to issue VAT invoices when selling to other businesses. They can choose between an electronic invoice or a paper one; both must include the VAT identification number, the VAT amount charged, and any other details required by the specific member state.
A few general rules apply across the whole EU:
- Paperless invoices are treated the same way as paper invoices.
- Companies can store invoices in whichever format and location they prefer, as long as they remain accessible.
- Businesses are free to send electronic invoices, subject to acceptance by the recipient.
If you need to check the requirements of a specific country, visit the official EU website, which lists the invoicing rules country by country.
VAT Invoices vs Other Business Documents
Sales tax and VAT are terms that cause a lot of confusion among business owners, so it is worth clarifying the difference. Sales tax is paid only once, at the final stage of a supply chain, when a retailer sells to a consumer. It is not charged again if the goods are resold along the way. VAT, on the other hand, is charged at every stage of the supply chain - suppliers, manufacturers, distributors, and retailers all pay it.
VAT invoices are only issued once a sale actually happens, which means documents such as a proforma invoice, an order confirmation, or a quote do not count as VAT invoices:
- Proforma invoice - a proforma invoice states the price of goods or services and is issued before payment is made.
- Order confirmation - this document does not provide sufficient evidence to claim VAT. Its purpose is to acknowledge an order, and it can serve as an indication of planned business spend.
- Quote - a quote is an estimated price for goods or services. VAT cannot be recovered on a quote, since it is only a commitment to a price and the buyer still has to decide whether to place the order.
To sum up, a VAT invoice is issued only when a sale takes place and a payment obligation arises, and it confirms exactly how much VAT is due.
Frequently asked questions
What is the difference between a VAT invoice and a sales tax invoice?
Sales tax is charged only once, when a retailer sells to a final consumer, while VAT is charged at every stage of the supply chain, from suppliers to retailers.
What information must a VAT invoice include?
A VAT invoice needs the business name and address, VAT number, invoice date and number, client details, the VAT rate, amounts per item, the total due, and the currency used.
When do I need to register for VAT in the EU?
You must register once your taxable turnover crosses the threshold set by the country where your business operates, or once your cross-border sales to consumers exceed 10,000 EUR.
Is a proforma invoice the same as a VAT invoice?
No. A proforma invoice shows the price of goods or services before payment is made, while a VAT invoice is issued only after a sale actually takes place.